On September 24, 2026, a bankruptcy auction will be held over Zoom for the assets of three e-commerce brands, Body Merry, a skincare and beauty label, BRI Nutrition, a supplements brand, and Refresh Filters, which sells replacement water and air filters. All three businesses failed. None of their warehouses, inventory, or physical operations are what’s being sold. According to the auction listing, what’s actually on the block is a list that reads almost entirely as intellectual property: trade names, design marks, copyrights, customer lists, digital content, and the “related goodwill” built up around each brand.
This is not an unusual story in bankruptcy practice, it’s closer to the default pattern. And for management and finance students specifically, rather than lawyers, it’s a genuinely useful window into something that doesn’t always get covered clearly in a standard MBA curriculum: intellectual property isn’t just a legal protection sitting in a filing cabinet. It’s frequently a company’s single most durable, most transferable financial asset, the one piece of the business that survives even when everything else about the company has failed.
The pattern shows up constantly, once you know to look for it
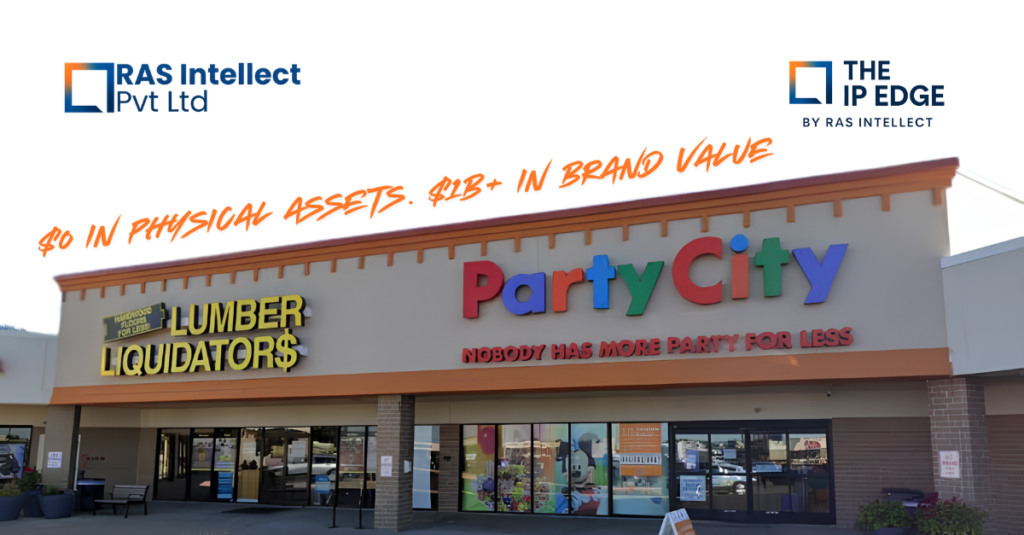
Look at any major retail or consumer bankruptcy from the last few years and the same structure tends to repeat. When Party City filed for Chapter 11 in early 2025, after four decades as a household name in party supplies, its physical retail operations wound down, but its intellectual property and wholesale operating assets were sold separately to an entity called Ad Populum, in a deal explicitly structured “to preserve legacy in the multibillion dollar party supply industry,” as the company’s own announcement put it, rather than to preserve the specific stores or the balance sheet that had gotten it into trouble.
Ad Populum is worth pausing on, because the company is essentially a case study in this exact idea taken to its logical business model. It has built a genuinely large, real portfolio, NECA, Rubies Costumes, Enesco, LLC, Kidrobot, WizKids, Smiffys, Graceland licensing, and, as of earlier this year, Toys”R”Us Canada’s trademarks, largely by acquiring the intellectual property of brands that failed operationally for reasons that had nothing to do with whether consumers still recognized and trusted the name. A failed capital structure, a mismanaged supply chain, or unsustainable debt doesn’t erase decades of brand recognition. It just means the entity that built that recognition can no longer afford to keep operating, which is a different problem entirely from the brand no longer being valuable.
FAT Brands’ 2026 Chapter 11 case shows the same logic playing out inside a single restaurant conglomerate rather than across an industry. Rather than liquidating as one company, its roughly eighteen-brand portfolio was split apart and auctioned by individual brand line: Hot Dog on a Stick sold separately for $8 million, Elevation Burger for $2.5 million, with Twin Peaks Restaurants and other business lines sold as their own distinct transactions. The company’s overall capital structure had failed. Several of its individual brands, considered as standalone trademarks with their own customer recognition, clearly still had buyers willing to pay real money for them.
Why this happens: IP is decoupled from the operations that failed
The underlying reason is straightforward once it’s named directly. A trademark’s value comes from consumer recognition and goodwill, an asset that lives in the minds of customers, not from the specific factory, lease, or management team that happened to be running the company when it collapsed. A bankruptcy trustee’s legal obligation is to maximize recovery for creditors, and intellectual property is very often the most liquid, most cleanly transferable line item available precisely because it can be sold to an entirely new owner without needing to also acquire the operational baggage that sank the original business.
This is also why intellectual property increasingly shows up as its own explicitly identified line item in healthy company transactions too, not just bankruptcies. Under standard purchase price allocation rules in M&A accounting, an acquirer generally has to separately identify and value intangible assets like trademarks, patents, and customer relationships, rather than lumping the entire premium paid into a single generic “goodwill” figure. Three broad valuation approaches are typically used to do this: the cost approach, essentially what it would take to recreate the asset from scratch, the market approach, based on comparable transactions or observed royalty rates for similar IP, and the income approach, which forecasts the future cash flow or royalty savings the asset is expected to generate, and is generally treated as the most rigorous method for a well-established brand or patent.
The practical takeaway for anyone building or running a business
For a management student who will eventually run a business unit, evaluate an acquisition target, or sit inside a distressed company’s restructuring process, the lesson underneath all three of these examples is the same one: intellectual property is not a compliance afterthought that sits next to the real financial assets on a balance sheet. In a surprising number of failed businesses, it is the real financial asset, the one line item still capable of returning meaningful value to creditors, or of giving a new owner a genuine head start rather than a blank sheet of paper. Understanding how that asset gets identified, valued, and separated from a failing operation isn’t a niche legal skill. It’s a core part of understanding how modern business value actually works, on the way up, and, just as often, on the way down.
Sources consulted for this piece: GlobeNewswire and TheStreet (Body Merry, BRI Nutrition, and Refresh Filters bankruptcy auction, September 2026); PR Newswire (Party City’s 2025 Chapter 11 sale to Ad Populum); Ad Populum LLC’s own corporate materials and licensing industry press coverage of its brand acquisitions; Wikipedia (Toys “R” Us Canada); and reporting on FAT Brands’ 2026 Chapter 11 case and its individual brand sales. General valuation methodology draws on widely used, standard approaches referenced across multiple independent business valuation sources. This piece was independently researched and written; no text has been reproduced from any source beyond the short attributed quote above.